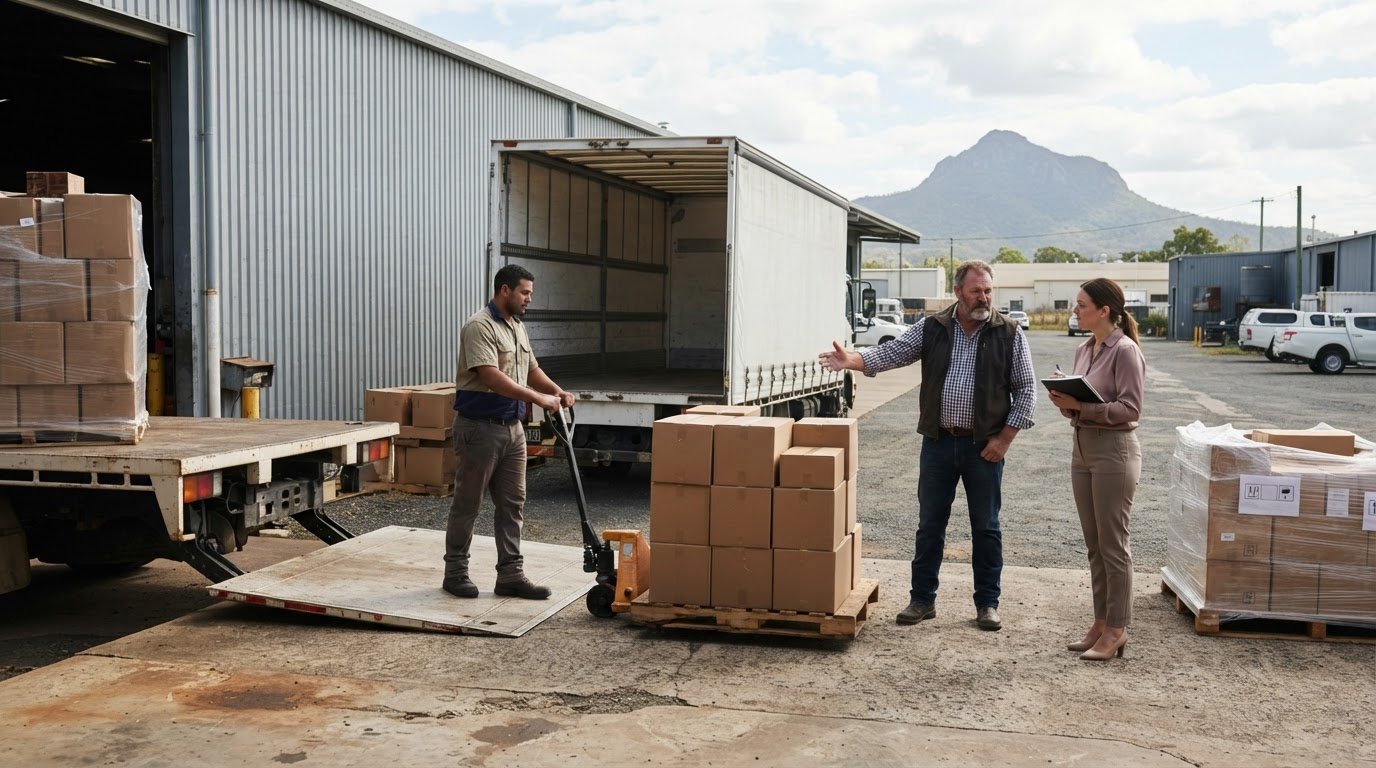
A profitable business can still run short of cash when bills fall due before customers pay. Cash flow is the net amount of cash moving into and out of a business, and the practical answer to how to improve business cash flow is to better manage when money arrives and when it leaves. That means staying on top of invoices, agreeing workable supplier terms and planning upcoming costs.
When you’re juggling customers, staff and daily decisions, cash flow planning can easily slip down the list. But a clearer view of money coming in and going out can help you spot a squeeze sooner and make more confident choices. This guide explains cash flow and practical ways to manage it, from improving payment processes to planning major costs. For small businesses in Rockhampton, these steps can bring more structure to the numbers behind everyday decisions.
Key Takeaways
- Align supplier due dates with customer payment timing, and discuss terms early to protect cash without straining relationships.
- Use a regular cash flow forecast to map expected money in and out, and prepare for quieter trading periods.
- Send invoices promptly, make payment terms clear and follow up overdue accounts consistently.
- Consider leasing equipment you need temporarily to spread its cost and preserve working cash.
- Review stock, regular expenses and planned purchases to identify practical ways to free up cash.
1. Negotiating supplier payment terms
Payment timing can create a cash gap even when sales are steady. For example, a business might give customers 30-day payment terms while suppliers expect payment within seven days. Money leaves before the related sales income arrives. Map customer receipts against supplier due dates, then identify which bills create the tightest weeks. That simple comparison gives you a practical starting point for negotiating terms.
Speak with suppliers before a cash squeeze develops. Explain your usual ordering pattern and payment cycle, then propose terms that better match when customer payments arrive. You could ask to move from net 30 to net 45 or net 60, or discuss net 60 or 90 days for suitable purchases. These are negotiation examples, not automatic entitlements. Keep communication regular and agree on dates your business can meet.
Choose payment timing carefully once terms are agreed. Paying every bill as soon as it arrives may unnecessarily reduce cash on hand, while paying late can damage supplier relationships. Use electronic payments to schedule a bill for its due date, when that timing suits your cash position and the supplier’s terms. If you have spare funds, ask whether an early-payment discount is available. Compare the saving with the value of keeping that cash available.
Review the customer side of the cycle too. Before agreeing to sell on credit, conduct a credit check and consider whether the customer’s payment history supports the proposed terms. Set clear due dates in client contracts or service agreements, and repeat those dates on each invoice. For new clients, consider shorter terms, such as net 15 rather than net 30, if they fit the arrangement and your business needs.
Make prompt payment straightforward. Offer practical options such as bank transfer, PayID, BPAY or card payment, and use e-invoicing with automatic reminders to reduce missed invoices. An early-payment discount can encourage customers to pay sooner. For example, consider a 2% discount for invoices paid within 10 days, then assess whether the earlier receipt is worth the discount to your margins. State the offer and its deadline clearly.
Before changing payment terms, consider both sides of the decision. A cheaper supplier may not be a better choice if quality suffers, and a discount may not help if it ties up cash needed for wages or other bills. For larger costs, discuss a payment plan. A sound arrangement balances available cash, reliable supply and business relationships, rather than shifting pressure from one week to another.
2. What Is Cash Flow?
Cash flow is the net amount of cash entering and leaving a business. It differs from profit: an invoice may record revenue before the customer pays, while rent and supplier bills still require cash. A business can therefore be profitable on paper and still struggle to meet its obligations. Track when money arrives and leaves, not just total sales.
Cash moves through operating, investing and financing activities. Operating cash covers the core trading cycle, including customer receipts and routine expenses. Investing cash includes buying or selling assets, while financing cash includes borrowing and repaying debt. Reviewing these movements regularly helps explain changes in the bank balance and whether normal operations are generating enough cash.
A weekly or monthly forecast maps expected inflows against outflows. Start with the current bank balance, then record likely customer receipts and dated expenses, including wages, rent, tax and supplier bills. Use actual payment history where possible, and update the forecast when a customer pays late or a cost changes. That makes the forecast a working tool, not a one-off spreadsheet.
For a 13-week cash flow forecast, enter the opening balance and list expected receipts and payments by week. Calculate the closing balance for each week, carry it forward as the next opening balance, and revise the figures regularly against actual transactions. If a low point appears, identify its cause early, then consider adjusting discretionary spending, timing purchases or following up expected receipts.
GST, PAYG withholding and superannuation can place pressure on cash when payment deadlines coincide with other bills. From 1 July 2026, employers must pay super contributions each pay cycle rather than quarterly, so forecasts should reflect that timing. Record amounts set aside for tax separately from money available for everyday expenses.
Government grants and tax concessions can support eligible businesses, but a forecast should count them only when approval and payment timing are clear. For unpaid Super Guarantee Charge, the Australian Taxation Office says lodging by the due date may allow a business unable to pay in full to arrange instalments. Build quiet periods into forecasts using seasonal sales patterns, then plan cash reserves before revenue dips.
Inventory can tie up working cash. Compare stock on hand with recent sales and expected demand, then adjust orders to avoid holding too much of slow-moving stock. A Rockhampton business with seasonal trade, for example, can use past sales patterns to plan purchasing ahead of a quieter period. Regular cash flow analysis helps distinguish a temporary seasonal dip from an ongoing shortfall.
Business Accounting and Advisory can help turn financial reports and forecasts into practical decisions about upcoming cash needs. If you’re unsure how to interpret changing balances or plan for a quieter period, Business Wise offers support to help you make sense of the figures and plan your next steps.
3. Accounts receivable and invoice collection
An unpaid invoice may appear as revenue in your records, but it can’t pay wages or operating expenses until the customer pays. Send invoices as soon as agreed work is complete, and make each one easy to understand. Include the customer’s details, a description of the work, the amount due, payment instructions and a clear due date. For a Rockhampton trade business, invoicing as soon as a job is signed off avoids leaving completed work unbilled.
Make payment straightforward with electronic invoices and familiar payment methods. Accounting software can help you prepare consistent invoices, record when they’re sent and identify overdue accounts. Set reminders for approaching due dates, then follow up late payments regularly. Ask whether an invoice is awaiting approval, contains an error or needs supporting documents. Finding the hold-up helps you choose an appropriate next step instead of sending repeated generic reminders.
For larger jobs, deposits or staged invoices can bring in cash before final delivery. Link each instalment to a defined milestone, such as ordering materials or completing a project stage. A contractor, for example, could invoice when a specified deliverable is ready rather than waiting until the whole project ends. Set out milestones and payment dates in the agreement so both parties know what triggers each invoice.
Automated expense tracking helps complete the picture. Record costs in accounting software, assign useful categories and match entries against bank transactions. Attach receipts so the reason for each expense remains clear. This gives you a more current view of money due in and out, helping you plan purchases without relying on memory or waiting for month-end paperwork.
If payments are often delayed, trace the process from completed work to money received. Check where time is being lost: invoice preparation, customer approval, missing details or follow-up. If invoices wait for one staff member to return, for instance, assign responsibility to the person who completes each job. These process improvements are practical ways to improve business cash flow by reducing avoidable delays between work and payment.
Invoice factoring is one way to access cash sooner. It involves selling unpaid invoices to a third party at a discount. Compare the amount you would receive with the value of waiting for the customer to pay, and consider the effect on customer relationships. Short-term borrowing is a separate option: weigh its repayment schedule and interest against expected receipts. Neither replaces sound collection routines, but each may suit a different cash timing issue.
Keep a record of outstanding invoices that shows the amount due, due date, last contact and next action. Review it regularly and use the pattern to guide decisions about payment processes and expenses. For a business looking at how to improve business cash flow, this record can show whether late receipts are occasional or part of a recurring collection problem.
4. Leasing equipment and property to preserve working cash
Buying equipment outright can use cash needed for wages, stock or other bills. Leasing or hiring spreads an asset’s cost over time, which may help preserve working cash. This can suit a Rockhampton business that needs equipment for a short project or wants to avoid a large upfront payment. Compare the payment schedule with expected income before committing.
Leasing isn’t automatically cheaper than buying. Compare the total payments over the period you expect to use the asset with its purchase cost and the cash remaining under each option. For example, a business planning to use a machine for one project can compare hiring it with buying equipment it may not use regularly afterwards. Include the agreement’s length and any ongoing obligations in your decision.
Property decisions also need a cash flow view. A business moving into a larger workspace can compare lease commitments with expected occupancy needs and projected receipts. Include proposed payments in a cash flow forecast alongside rent, utilities and other regular costs. This shows whether the business can support the commitment in the coming months, including during a quieter trading period.
Consider the asset’s role before leasing. List the equipment needed for current work, how often it will be used and whether demand is likely to continue. A seasonal business, for instance, may need specialised equipment only during peak periods. Hiring for that period may preserve cash for other needs, while an asset used regularly warrants a closer comparison of buying and leasing.
Refinancing an existing asset may change the timing of cash outflows, but consider it only if a lender can offer better terms. Compare the proposed terms with the current arrangement and assess how repayments fit the forecast. Selling an idle asset is another possible way to release cash. Before selling, consider whether the business will need to replace it for upcoming work or growth.
Base the comparison on the business’s financial records. Use accounting software or a cash flow forecast to model payment dates under each option, then assess the effect on planned purchases and operating costs. This makes the decision about more than the lowest instalment. A smaller regular payment can still create a longer commitment, while buying can use cash the business needs elsewhere.
For each asset, note its business purpose, expected use and effect on available cash. Then compare leasing, hiring, buying, refinancing or selling against those factors. This encourages deliberate investment instead of committing cash before the need is clear. If the forecast shows little room for repayments, revisit the timing or scope of the purchase before signing an agreement.
5. Cash flow management strategy
Good cash flow management connects daily choices with the business’s longer-term position. A profitable month can still leave little cash if customer payments arrive after major bills. Use a rolling 12-week forecast to spot pressure ahead, then assign an action to each likely shortfall. For example, bring forward a planned customer follow-up or delay a discretionary purchase.
Start by separating essential costs from expenses you can adjust. Review rent, utilities, insurance, subscriptions and supplier arrangements, then identify changes that could preserve cash without disrupting operations. A Rockhampton retailer might reduce excess stock that is slow to sell, while a service business could review unused software subscriptions. Base each decision on actual use and business needs, not on cutting costs for their own sake.
Check which products, services and customers contribute most to available cash. Sales volume alone can hide weak margins if direct costs are high or payment is slow. Compare revenue, related costs and collection patterns, then focus on work that supports both margin and timely receipts. If a price change is being considered, model a 5% increase and assess its possible effect on revenue and customer retention before implementing it.
Build a cash reserve gradually by setting aside part of your revenue when receipts come in. Keep money intended for tax obligations separate from funds for routine operating costs. This can reduce the risk of treating money needed for GST, PAYG withholding or BAS payments as available spending cash. Check planned purchases against the forecast so a large commitment doesn’t create unnecessary pressure during a quieter trading period.
Test the plan against less favourable conditions, such as a late-paying customer, lower sales or an unexpected repair. Note which bills would still fall due and what spending could be changed first. If you’re considering external working capital, compare the repayment schedule and interest with expected receipts. A line of credit charges interest on the amount used, while an overdraft or invoice financing has its own conditions and obligations. Borrowing can bridge a timing gap, but it won’t fix a persistent gap between income and costs.
Make cash flow review a regular management habit. When actual results differ from the forecast, update the assumptions and decide whether your response worked. This creates a practical cycle: review the position, choose a strategy, then measure its effect. Business Wise provides accounting and advisory support to help you interpret results and plan next steps.
Business Wise
As a family-owned firm, Business Wise understands the care and commitment involved in running a local business. Its Business Accounting and Advisory, Bookkeeping & BAS Services, and Tax Advisory can help you understand your figures and plan with a clearer view of your finances.
If you’re facing a cash flow challenge or planning your next step, you don’t have to work through the numbers alone. Contact Business Wise to discuss accounting and advisory support for your business.
Make cash flow part of your regular decisions
Improving cash flow is an ongoing management habit, not a one-off fix. Set a regular time to review your position, note what has changed and decide what needs attention next. This turns the question of how to improve business cash flow into practical decisions that support the business you’re building, rather than another task to revisit only when money feels tight.
If you’d value a hand making sense of your numbers, Business Wise offers Business Accounting and Advisory, Bookkeeping & BAS Services, and Tax Advisory. These services can help bring financial records and planning into a clearer view as your business moves through its next stage. Contact Business Wise to discuss cash flow and the support that fits your business. Steady, informed decisions can help you move forward with greater confidence.
Frequently Asked Questions
What Is Cash Flow?
Cash flow is the movement of money into and out of a business over time. It shows whether cash is available for upcoming commitments, rather than simply whether sales exceed expenses on paper. For example, a completed job may contribute to reported revenue, but the business can’t use that money until the customer pays. Tracking timing helps owners see how trading activity affects day-to-day financial capacity.
What are the most effective ways for an Australian small business to improve cash flow?
Start with the cause of the pressure, then address the relevant part of the cash cycle. If work is profitable but cash arrives late, improve invoicing and collection processes. If costs rise before seasonal sales, adjust purchasing and plan spending around expected demand. A Rockhampton business can compare bank activity with its forecast and trading patterns, then prioritise changes that ease the next expected shortfall.
What are the best ways to manage accounts payable and supplier payment terms?
Keep a central record of approved bills, due dates, disputed charges and expected payment dates. Review it alongside your cash position before scheduling payments, and resolve invoice discrepancies early so they don’t unexpectedly become overdue. For recurring purchases, discuss terms that reflect your trading cycle and record any agreed changes. A consistent process helps owners avoid duplicate payments and communicate more clearly with suppliers about outstanding accounts.
How can a business reduce inventory and working capital costs?
Use sales and stock records to identify items that remain unsold or no longer meet customer demand. Adjust future orders to reflect current sales patterns, and consider ordering after a customer purchase when the product and delivery timing allow. For example, a retailer can review slow-moving lines before placing its next order instead of automatically replenishing every item. Keep service quality and reliable supply in mind when changing stock levels.
What cash flow funding options are available to Australian businesses, and what do they cost?
Options may include an overdraft, a line of credit, invoice financing, a business credit card or borrowing. Costs depend on the facility’s terms, interest, fees and amount used, so compare the total repayment commitment with expected cash receipts. Invoice factoring, for example, turns unpaid invoices into earlier cash at a discount. Business Wise provides accounting and advisory support, not business loans.
How can a business identify and manage cash flow risks, including seasonal fluctuations?
Watch for warning signs such as repeated forecast shortfalls, delayed customer payments, rising costs or dependence on a small number of customers. Compare actual results with expectations regularly, then model changes such as weaker seasonal sales or a major repair. If a quieter period is predictable, plan spending and cash reserves before it begins. This gives you time to adjust purchasing or postpone discretionary commitments.
Disclaimer
“The information on this website is general in nature and is provided for information purposes only. It is not legal, financial or professional advice. You should obtain specific, independent advice relevant to your circumstances.”
You must be logged in to post a comment.